Royal Caribbean Raises 2026 Profit Forecast After Earnings Beat
For 2027, Hero of the Seas is scheduled for seven-night Miami cruises, while Icon of the Seas will move to Galveston and Celebrity River operations are due to begin.
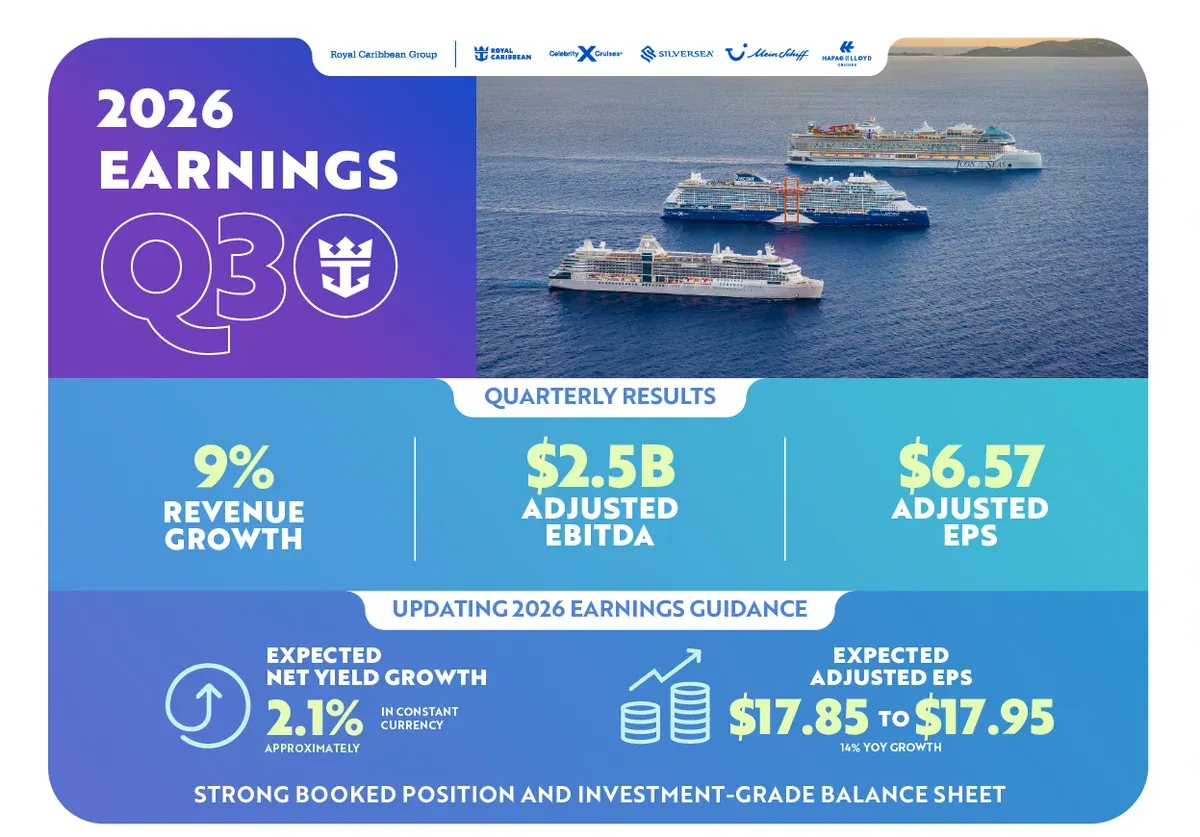
Royal Caribbean Group shares rose more than 6% in Tuesday trading after the cruise operator beat third-quarter earnings expectations and raised its full-year profit forecast. The company now expects 2026 adjusted earnings per share of $17.85 to $17.95.
Third-quarter adjusted EPS reached $6.57, compared with $5.75 a year earlier and the $6.36 consensus compiled by Visible Alpha. Revenue increased 8.8% year over year to $5.59 billion, narrowly below expectations.
The revised annual outlook compares with Royal Caribbean’s previous range of $17.73 to $17.87 and Visible Alpha’s $17.79 consensus. Tuesday’s advance brought the stock’s year-to-date gain to about 7%; Carnival Corp. and Norwegian Cruise Line Holdings shares also rose.
Jason Liberty, Royal Caribbean Group’s chairman and chief executive officer, said that “while it is still early, 2027 bookings are pacing ahead of historical levels at higher rates.”
Bookings and passenger volumes increase
Booking volumes across the group, whose cruise brands include Royal Caribbean International, Celebrity Cruises and Silversea, increased by a mid-teens percentage year over year since the previous earnings call. Bookings for 2027 sailings rose by a high-teens percentage, while the booked position for both years was ahead of the prior year at record rates, Liberty said.
Better-than-expected close-in demand in Europe and the Caribbean helped third-quarter net yields exceed company guidance. Net yields increased 0.9% as reported and 0.6% in constant currency, although gross margin yields declined 0.8%.
The company carried approximately 2.7 million guests, up 9%, as capacity increased 8%. Load factor was about 112%, and passenger cruise days reached 16.69 million, an increase of 1.34 million from the comparable quarter.
Onboard and pre-cruise revenue rates rose year over year. Liberty told analysts that onboard spending had exceeded management’s expectations, while fourth-quarter pre-cruise revenue rates were also booked ahead of the previous year.
Quarterly net income totaled $1.73 billion, or $6.45 per share. Adjusted EBITDA was approximately $2.5 billion, with a margin of about 45%.
Expense timing and fuel affect the outlook
Part of the earnings outperformance came from costs moving into the final quarter. Third-quarter net cruise costs excluding fuel declined 1.9% per available passenger cruise day as reported, or 1.8% in constant currency. Naftali Holtz, executive vice president and chief financial officer, attributed the better-than-expected cost result to expense timing, which added about five cents per share relative to guidance.
Higher projected fuel costs and unfavorable currency movements partly offset the stronger quarter in the revised annual forecast. Royal Caribbean expects full-year fuel expense of approximately $1.35 billion. Fourth-quarter fuel expense is projected at $379 million, based on consumption of roughly 463,000 metric tons, with 58% of consumption hedged.
For the quarter ending in December, management forecasts adjusted EPS of $3.48 to $3.58, below the $3.66 consensus cited by Seeking Alpha. Capacity is expected to increase 5%, with net yields growing 4.2% to 4.7% in constant currency. Net cruise costs excluding fuel per available passenger cruise day are projected to decline 0.9% to 1.4% on the same basis.
The yield outlook includes benefits from deployment mix, dry-dock timing and a more favorable comparison with the previous year. For 2026 overall, management expects capacity growth of 6.6%, constant-currency net yield growth of approximately 2.1% and roughly flat unit costs excluding fuel.
Royal Caribbean ended the quarter with $7.4 billion in liquidity and leverage below three times. During the quarter, it issued $1.25 billion of senior unsecured notes due in 2034, using the proceeds to repay some floating-rate term loans and debt maturing in 2027.
Heading into 2027
Management expects capacity to grow 4.5% next year through new ships and fewer capacity days lost to dry docks. Hero of the Seas is scheduled to enter the seven-night Miami program, with Icon of the Seas moving to Galveston, while Celebrity River operations are also due to begin.
Holtz expects yield growth to be weighted toward the second half of the year, with approximately 200 basis points of structural headwinds in the first quarter, including dry-dock timing. Liberty said the company remains on course for its Perfecta target of 20% compound annual growth in adjusted EPS from 2024 through 2027, or a “$20-handle” next year, based on the forward fuel curve.
Royal Caribbean agreed in September to acquire a 50% interest in Sandals and Beaches Resorts for approximately $3 billion. Holtz expects the investment to be immediately accretive, but its contribution to 2027 earnings to be immaterial because of closing timing and the reporting lag.
The transaction is expected to close in early 2027, subject to regulatory approvals and customary conditions. Royal Caribbean will account for the stake under the equity method with a one-quarter lag and incorporate its earnings contribution into guidance after closing.