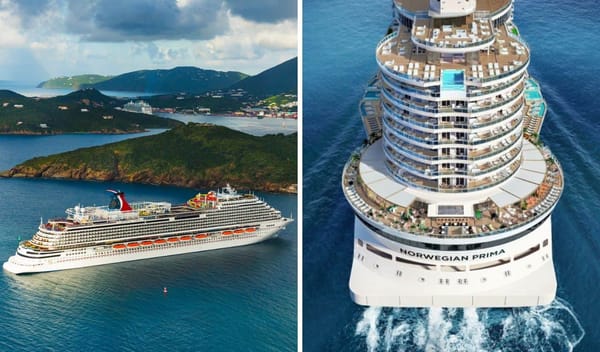
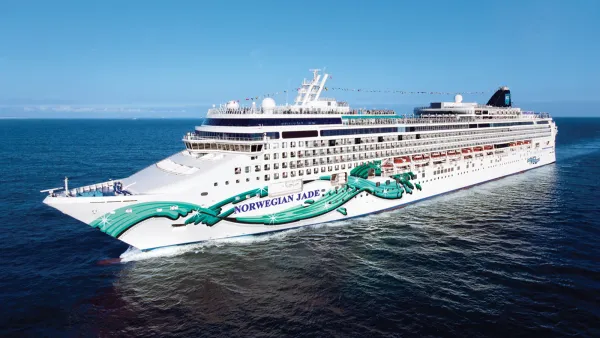
Norwegian Cruise Line Resets Early Booking Prices to Rebuild Demand
NCLH expects third-quarter results to exceed its July forecast of $0.90 in adjusted earnings per share and $874 million in adjusted EBITDA, without issuing updated figures.
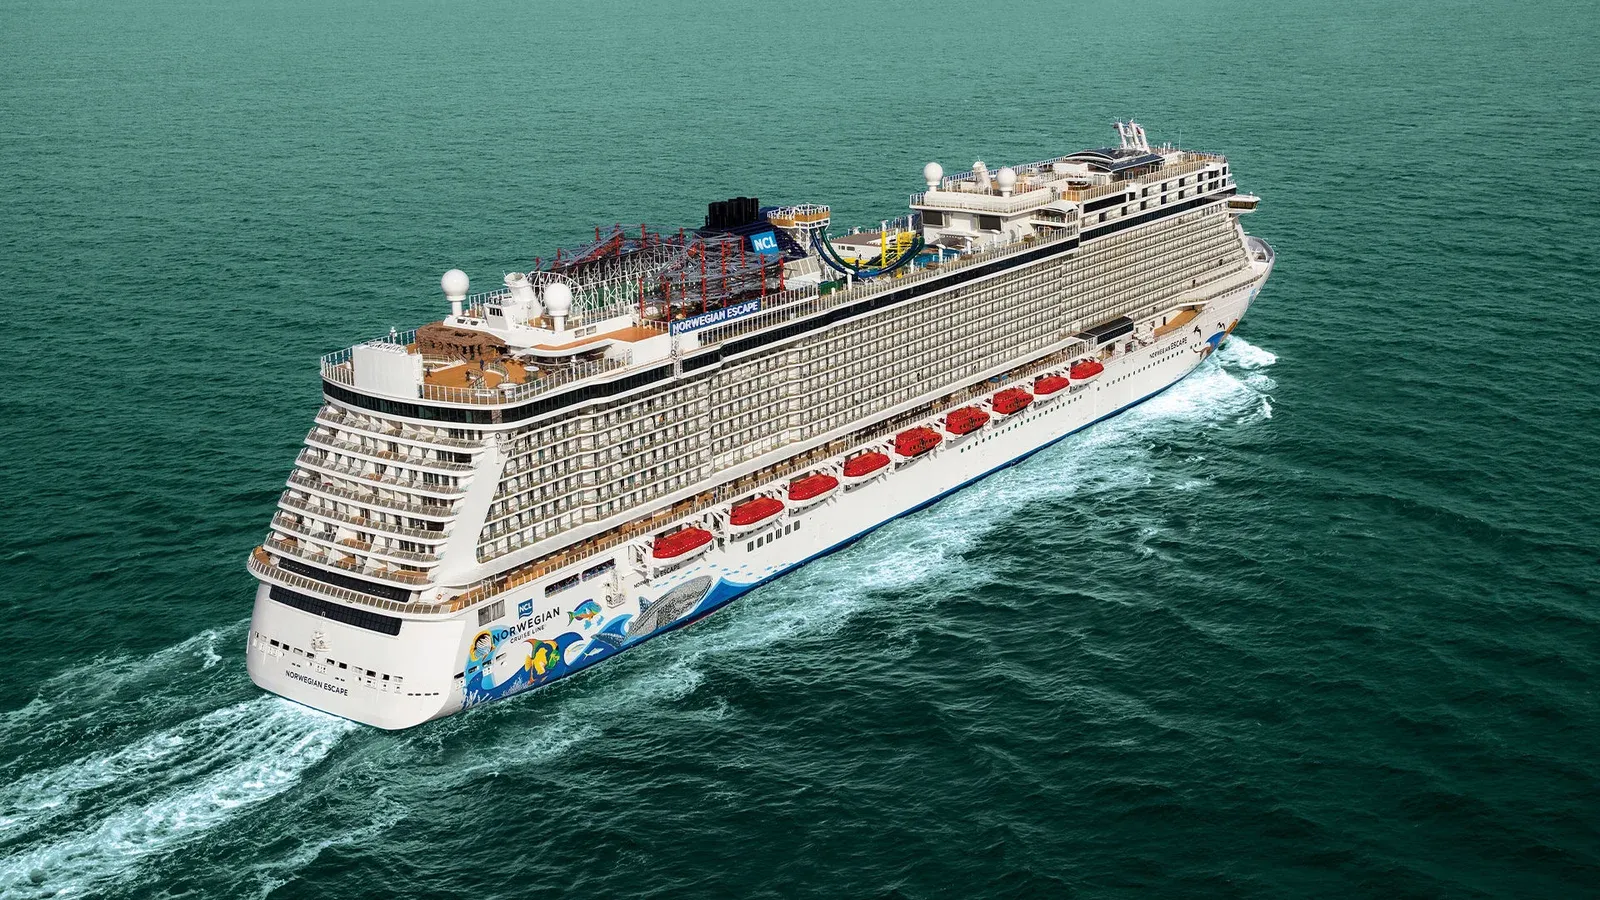
Norwegian’s stock bounced. Its pricing reset deserves more attention
Norwegian Cruise Line Holdings is moving to offer more competitive prices earlier in the booking cycle. I like that decision more than the stock’s latest rally. Management has identified pricing and marketing execution as problems at the Norwegian Cruise Line brand, and changing the booking approach addresses something the company can actually control.
That is a useful distinction in a week when strong results from Carnival helped lift cruise shares broadly. A healthier sector does not fix a brand’s sales execution.
NCLH’s second-quarter net yield declined 2.6%, and Chief Executive Officer John Chidsey described a turnaround focused on rebuilding demand at Norwegian. Oceania Cruises and Regent Seven Seas Cruises continued to perform well, according to management. The weakness was not uniform across the group.
European sailings also faced pressure as North American travelers contended with higher airfares and broader economic uncertainty. NCLH cannot set the price of a flight to Europe. It can make its own fares more competitive while passengers are deciding whether to book. That is a sensible place to start, even if sharper pricing alone cannot repair the marketing problems management has acknowledged.
A better quarter, but the same annual target
Wednesday brought encouraging company-specific news. NCLH said stronger-than-expected revenue should push third-quarter results above its July forecast of $0.90 in adjusted earnings per share and $874 million in adjusted EBITDA. It did not provide revised quarterly figures.
The company also reaffirmed, rather than raised, its full-year 2026 adjusted earnings target of $1.50 per share. That remained above analysts’ consensus of $1.37.
The revenue improvement deserves credit, and calling it evidence of progress is fair. Without a revised quarterly number or a higher annual target, declaring the Norwegian brand’s turnaround accomplished would get well ahead of the reporting.
The previous quarter showed why the distinction matters. Results released July 30 included earnings of $0.48 per share, above the $0.41 consensus but below the prior-year quarter’s $0.51. Revenue increased 4.9% to $2.64 billion, narrowly missing analysts’ $2.65 billion estimate. An earnings beat and uneven operating performance can exist in the same quarter.
Carnival supplied the backdrop for Tuesday’s rally
NCLH shares opened at $15.11 on Tuesday, September 29, 2026, up 5.6% from the previous close of $14.31. The NYSE-listed group finished the session 3.4% higher after surrendering part of that opening gain. Royal Caribbean shares also rose.
That trading session preceded Norwegian’s Wednesday update. The broader cruise-stock rally followed Carnival Corporation’s better-than-expected fiscal third-quarter results.
Carnival reported adjusted earnings of $1.43 per share on approximately $8.44 billion in revenue, both above analysts’ expectations. Revenue rose 3.5% year over year, and net income reached a record $1.9 billion.
Its booking figures were particularly strong. Third-quarter customer deposits increased nearly 7% from the previous year’s record despite flat capacity growth. Carnival also said booked occupancy and pricing for 2027 were at record levels.
Still, the outlook was not uniformly above expectations. Carnival raised its full-year adjusted earnings forecast to $2.24 per share from $2.22, while its fourth-quarter projection of $0.20 fell short of the $0.26 analyst consensus.
Those results support optimism about Carnival’s business. Norwegian’s own figures still have to establish whether its pricing changes are working.
The market’s enthusiasm remains qualified
Tuesday’s activity was lively. MarketBeat recorded purchases of 44,435 NCLH call contracts, 71% above the typical volume of 26,007. By midday, about 26.9 million shares had changed hands, compared with average trading volume of approximately 20 million.
Despite the rebound, NCLH remained down roughly one-third for the year and below its 50-day moving average of $17.06 and 200-day average of $18.28.
MarketBeat’s Tuesday data showed a consensus “hold” recommendation and an average price target of $20.50. Of 23 analysts covering the company, 15 rated it hold, five buy, two strong buy and one sell.
The recent calls were mixed. JPMorgan Chase cut its target to $13 from $17 on September 24 while retaining a neutral rating. Mizuho lowered its target to $17 from $22 on August 18, also maintaining neutral. TD Cowen went the other way, upgrading NCLH to strong buy on September 8.
Institutional investors held 69.58% of the shares. Previously disclosed investments included Elliott Investment Management’s first-quarter position, valued at approximately $246.6 million.
The financial obligations remain substantial. NCLH’s debt-to-equity ratio stood at 5.40, and the company projected net interest expense of $860 million to $880 million for 2027.
That makes the quality of the operating recovery important. More competitive early fares are a credible response to weak demand at the Norwegian brand. Winning bookings is necessary. Earning more from the sailings is what would give this turnaround substance.