Lindblad’s Longer Booking Window Gives It More Pricing Flexibility
For summer 2027, the 130-passenger Greg Mortimer will replace two smaller ships in Alaska, while Lindblad continues expanding its Amazon program.
Lindblad’s Longer Booking Window Gives It More Room on Pricing
Lindblad’s guests are booking an average of 11.9 months ahead, up from 9.5 months over the past 18 months. That extra 2.4 months is the detail I’d lead with in a quarter full of records. Earlier commitments give the company more visibility and, as chief executive Natalya Leahy put it, greater flexibility on pricing. That is a useful improvement in how the business runs.
The results give that improvement some substance. In the quarter ended September 30, 2026, the Lindblad segment recorded its highest third-quarter net yield at $1,398 per available guest night, up 6 percent from a year earlier. Occupancy rose from 88 percent to 91 percent, even with a 4 percent increase in available guest nights.
More capacity, higher occupancy and better yield make a persuasive combination. I like the emphasis on getting commitments earlier rather than simply celebrating how many berths were filled.
Leahy attributed the performance to changes in commercial operations, including revenue management and improved marketing. She said this was Lindblad’s third consecutive quarter above 90 percent occupancy.
“We are at the optimal occupancy level,” she said.
That is a sensible judgment to make when yield is setting records. A full ship should not become a more important objective than what the available capacity earns.
Pricing gains, with a useful distinction
Leahy said pricing increases had reached double-digit rates in many cases, while she expected yield growth to settle around the mid-single digits. Those are different measures, and the distinction matters. Double-digit increases on some bookings do not mean the whole business is producing double-digit yield growth.
Lindblad raised its full-year net yield growth forecast to 6–7 percent, from 5.5–6.5 percent. That is a measured upgrade, and the quarter’s performance supports it.
Onboard and extension revenue also increased 27 percent year to date. Leahy said that revenue stream still had substantial room to grow.
The earnings record needs its accounting context
Total company tour revenue reached $269.2 million, up 12 percent from the third quarter of 2025. The Lindblad segment generated $153.4 million, an 11 percent increase, supported by higher occupancy and additional capacity.
Land Experiences revenue rose 13 percent to $115.8 million as it carried more guests and operated additional trips. Lindblad and Land Experiences contributed $15.8 million and $13.2 million, respectively, to the year-over-year revenue increase.
Net income available to stockholders reached a quarterly record of $24.2 million, or $0.36 per diluted share, compared with a $49,000 loss a year earlier. But the prior-year quarter included a $23.5 million debt-extinguishment loss. That makes the headline earnings swing look much more dramatic than the underlying operating comparison. A $7 million increase in income tax expense partly offset the latest quarter’s improvement.
Adjusted EBITDA gives a cleaner view of the operating progress. It rose 12 percent to a record $64.1 million. Lindblad contributed $37.1 million, up $4.3 million, while Land Experiences contributed $27 million, up $2.5 million.
Costs rose, too. Lindblad faced higher voyage activity and fuel costs, additional marketing spending, and higher royalties following the final rate step-up under the National Geographic agreement associated with the National Geographic–Lindblad Expeditions co-brand. Land Experiences incurred higher operating and personnel costs as it ran more trips, alongside increased marketing expenditure.
More capacity will test that discipline
Leahy said deployment changes and expanded charter operations had delivered mid-single-digit capacity growth this year. She expects the charter-expanded business to keep generating growth in that range.
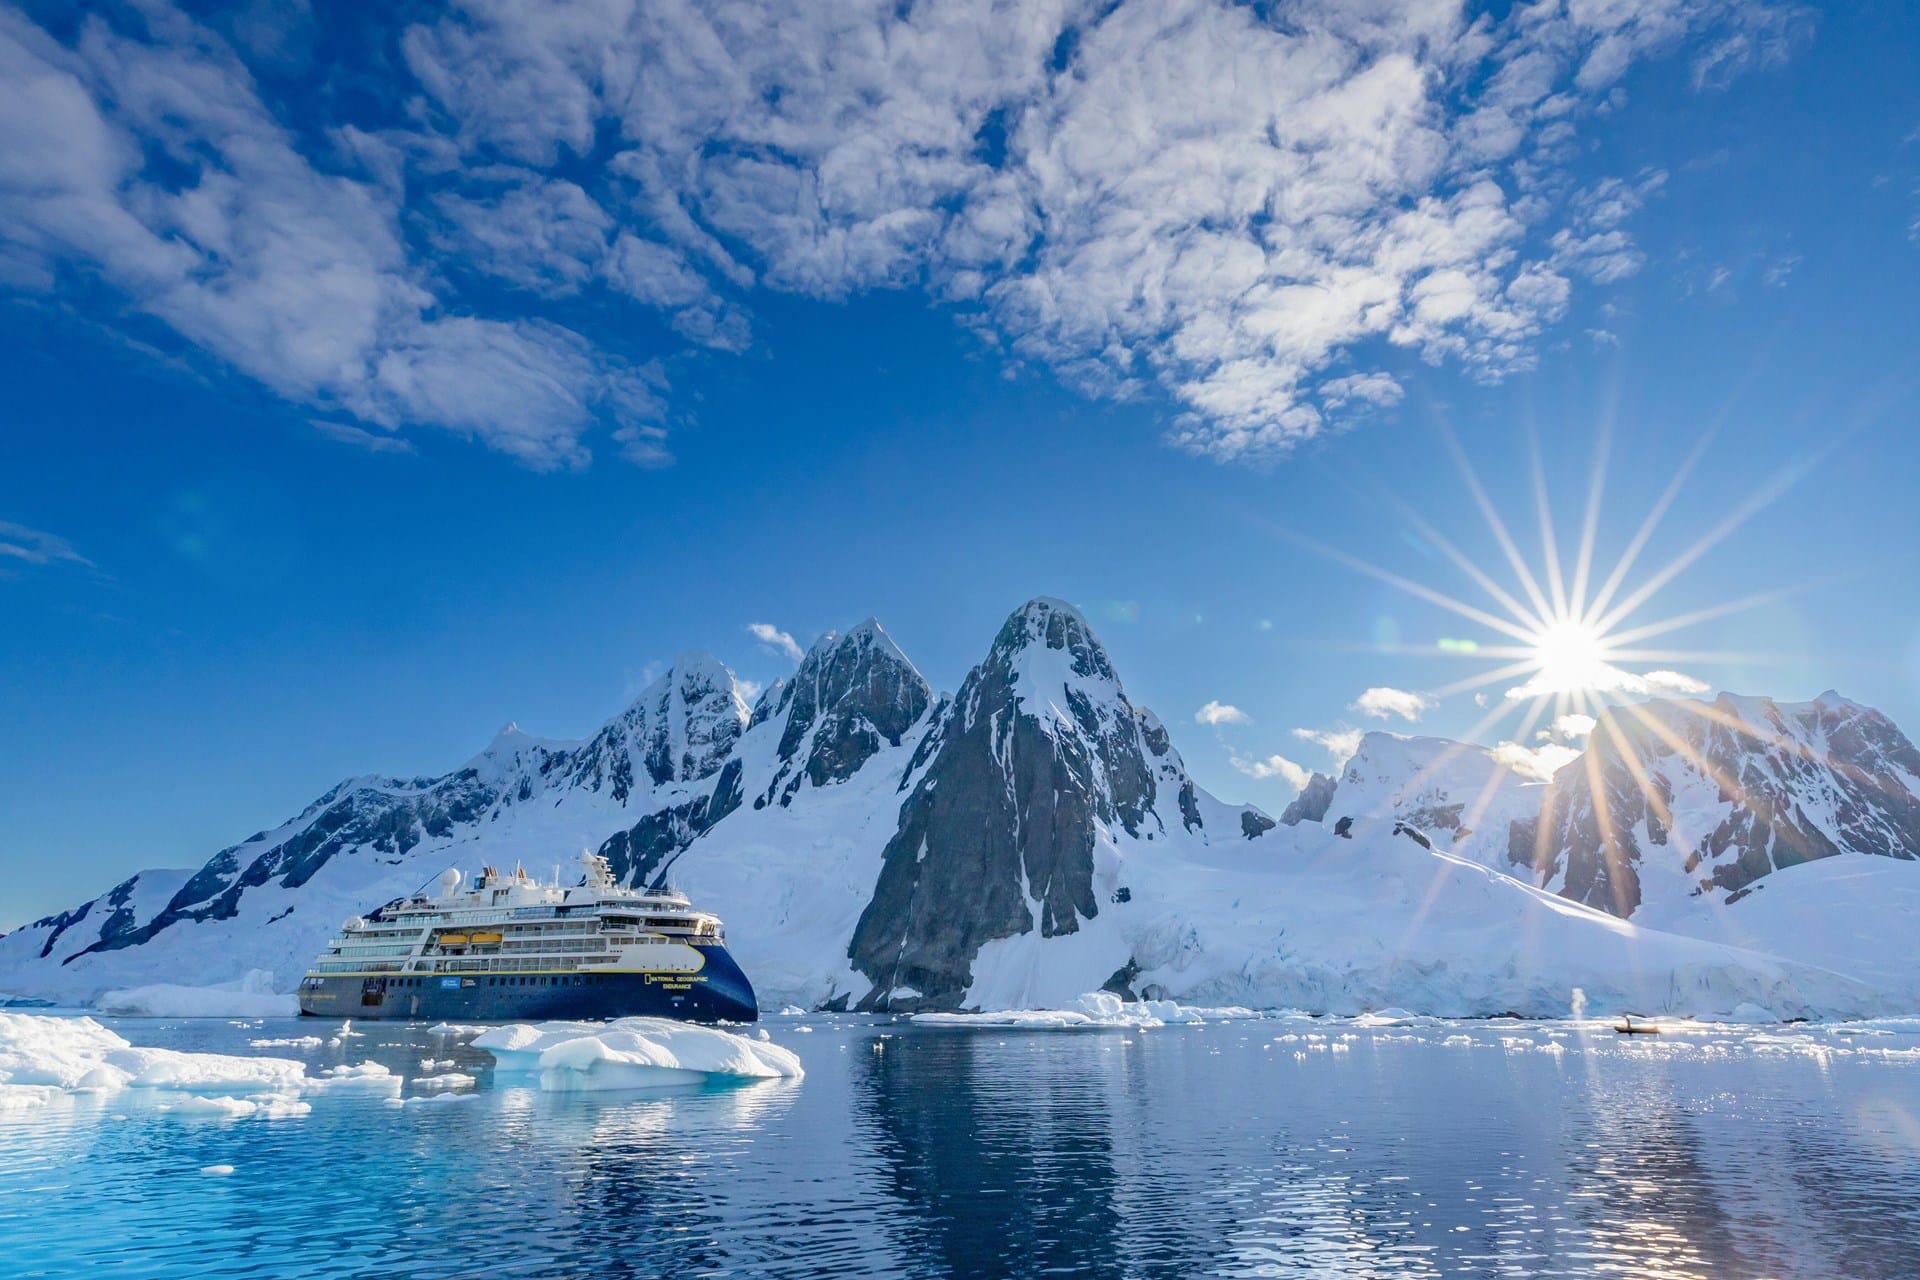
The company has expanded its Amazon program and is growing in Alaska. For summer 2027, Greg Mortimer, which typically carries 130 expedition passengers, will replace two smaller ships in Alaska.
Chief Financial Officer Rick Goldberg said the balance sheet supported further land acquisitions and fleet expansion through new builds, acquisitions and charters. Leahy said additional ship plans were close to being finalized, without disclosing which route the company would take.
That makes the longer booking window more consequential. Lindblad is preparing to add capacity while reporting stronger pricing and earlier commitments. I’d judge the next expansion by whether it preserves that combination, not by the number of berths announced.